Annuities / Fixed Index Annuities
A steadier way to frame retirement income.
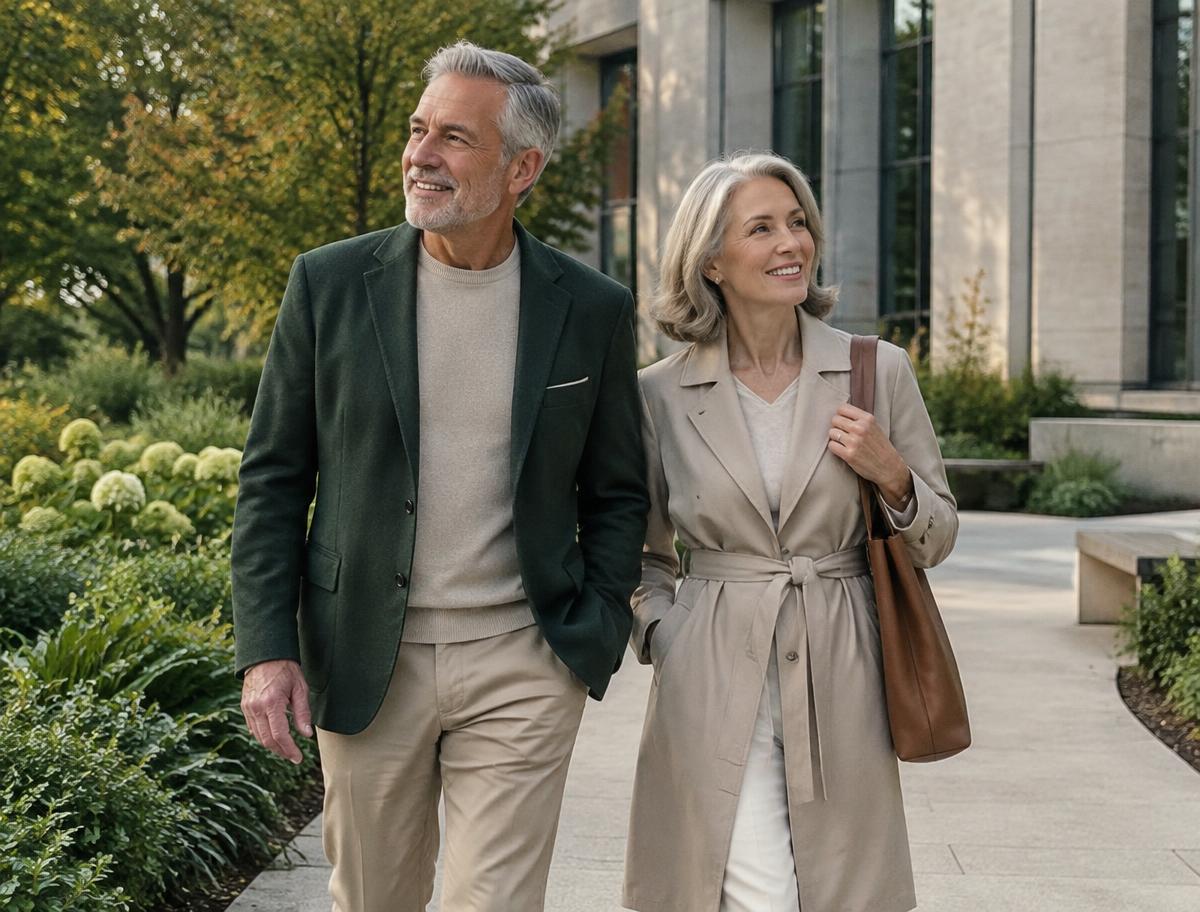
A fixed indexed annuity is a specialized insurance contract designed to help you accumulate wealth safely and convert it into predictable, tax-deferred retirement income. Unlike vehicles that expose your savings to market risk, an FIA completely protects your principal with a guaranteed 0% floor, ensuring you never lose a dime to market downturns. Instead, your growth is tied to an underlying market index, allowing you to capture market-driven gains up to specified contract limits (such as caps, spreads, or participation rates). It is an ideal solution for those seeking protected growth, flexible future payout options—including guaranteed income for life—and a reliable bridge toward a secure retirement.
Institutional Ecosystem & Strategic Partners
Who May Consider
When preservation becomes a priority.
An FIA may be worth exploring if you are approaching or currently in retirement with approximately $300K or more in qualified or non-qualified savings, and you want to:
- Protect Capital: Safeguard a portion of your hard-earned savings from late-stage market crashes.
- Secure Lifetime Income: Establish a predictable, guaranteed income stream to complement Social Security or pensions.
- Optimize Taxes: Benefit from tax-deferred growth while keeping your money compounding safely.
Note: Because annuities are long-term commitments, carefully weighing your immediate liquidity needs, investment time horizon, total asset mix, and insurer strength remains vital.
Misconceptions worth Understanding
- “No market loss” does not mean unlimited liquidity or guaranteed gains.
- An index-linked credit is not the same as owning stocks or receiving index dividends.
- Income rider values are often benefit bases, not cash values available as a lump sum.
- Rates and crediting terms can change within contractual limits.
- Guarantees depend on the financial strength and claims-paying ability of the issuing insurer.
Educational FAQ
Understanding how Fixed Indexed Annuities work.
How does a Fixed Indexed Annuity grow without stock market risk?+
A Fixed Indexed Annuity does not invest directly in the stock market. Instead, the insurance company places your principal into its general account and uses a portion of its corporate earnings to purchase options on market indexes like the S&P 500.
The Upside: If the index rises, your annuity is credited with interest based on that growth, up to certain limits (such as caps, spreads, or participation rates).
The Downside Protection: If the market drops, your contract hits a guaranteed 0% Floor. Your principal and previously locked-in gains remain completely safe, shielding you from any market losses.
Will my returns exactly match the performance of the linked index?+
No. An FIA is an insurance contract designed to balance growth and safety, not a direct market investment. Your earnings are calculated based on the index's movement but are modified by your specific contract's terms:
• Cap Rate: The maximum percentage of interest the annuity can earn during a specific period.
• Participation Rate: The percentage of the index's total gain that you are eligible to receive.
• Spread / Asset Fee: A flat fee percentage deducted from the index's growth before interest is credited.
How can an FIA provide a "guaranteed income floor" for life?+
After your annuity accumulates value, you can convert the contract into a stream of regular payments or utilize an optional Lifetime Income Benefit Rider. This allows you to turn on a predictable income stream legally guaranteed to pay you for the rest of your life, even if your account balance drops to zero.
Compliance Note: "Income" or "lifetime income" refers strictly to the guaranteed payment of lifetime payment amounts (LPAs). It does not refer to interest credited to the contract. Please consult with your tax advisor regarding the tax treatment of LPAs, which varies according to individual circumstances.
What is the difference between Qualified and Non-Qualified funds in an annuity?+
This depends entirely on the tax status of the money you use to fund the annuity:
• Qualified Funds: Money that comes from a pre-tax account, such as a Traditional IRA or 401(k). Your distributions from the annuity will be 100% taxable as ordinary income.
• Non-Qualified Funds: Money that comes from a post-tax account, like a standard savings or brokerage account. When you take distributions, only the earnings are taxed; your original principal is returned to you tax-free.
Can I access my money if an emergency comes up?+
Yes, but annuities are long-term contracts, so liquidity is structured. Most FIAs offer a free withdrawal provision, which typically allows you to take out up to 10% of your contract value each year without any penalties.
What are surrender charges and how do they work?+
If you need to withdraw more than the allowed penalty-free amount (usually 10%) during the early years of your contract, you will incur a surrender charge. These charges are a percentage fee that starts higher (e.g., 7% to 10%) and gradually scales down to 0% over a set timeline (typically a 5 to 10-year "surrender period"). Additionally, withdrawals taken before age 59½ may face a 10% IRS tax penalty.
What happens to the money in my annuity if I pass away?+
Unlike old-fashioned annuities that kept your money when you passed away, modern FIAs feature a built-in death benefit. If you pass away before you finish drawing down the contract, 100% of your remaining account value is passed directly to your named beneficiaries—completely bypassing the lengthy and expensive court probate process.